Across the MLS records included in this analysis, the 2021-2025 full-year series shows a higher raw median close price over time, a sharp reduction and later partial recovery in recorded event counts, and a shift in the median sale-to-export-list relationship. The 2026 row ends August 19 and is kept separate from full-year comparisons.
The useful insurance question is not simply, “What will the premium be?” It is whether an insurer is prepared to cover this property, for your intended use, by the date you become responsible for it—and what the policy will leave you responsible for.
Some lenders require home insurance before closing, and your mortgage commitment may require proof of fire or homeowners insurance. That makes the answer part of financing and closing readiness. It can also reveal a property issue while you may still have time to investigate it. Start the insurance conversation as soon as your offer is accepted, or earlier when the home has features that may require extra underwriting. FSRA’s mortgage-professional guide explains why the lender’s own requirements and documents must be checked.
First, keep the insurance products straight
Home or property insurance covers the home and other risks described in the policy. It is different from mortgage loan insurance, which protects the lender against borrower default, and from optional mortgage life, disability or critical-illness products. The Financial Consumer Agency of Canada explains those distinctions.
A quote is a starting point. Ask the insurer or broker what information is still outstanding, whether an inspection or corrective work is required, when coverage can begin and what document your lender or lawyer will need.
Build an accurate property file before asking for a quote
An insurer prices and accepts risk using the facts in the application. The federal consumer agency says underwriting can determine the coverage offered, exclusions and premium, and warns applicants to answer questions completely and honestly. A listing description is useful context, but it is not an insurance application.
Have the best available answers ready for questions such as:
What type of home is it, how old is it, and what is its approximate size and construction?
What are the age and type of the roof, electrical service, plumbing and heating systems?
Is there a wood-burning appliance, oil equipment, a sump pump or a backwater valve?
Will any part of the property be rented, used for short-term accommodation or used for a business?
Will the home be vacant between closing and occupancy, or left unoccupied for extended periods?
How close is the property to a fire hydrant or fire station, and is access seasonal or private?
If you do not know an answer, say so and find the appropriate document or qualified professional. The related Greater Sudbury home-inspection guide explains what an inspection can—and cannot—add to that property file.
Building settlement: Is the building covered for replacement cost, actual cash value or another defined basis?
Water: What coverage, limit and deductible apply to sewer backup and overland water? Do not assume either is included.
Contents and liability: What is covered, to what limit, and are high-value items restricted?
Temporary living costs: What additional living expenses are covered after an insured loss?
Exclusions and conditions: What is not covered, and what maintenance, occupancy or protective-device requirements must you meet?
The federal home-insurance guide notes that policies commonly exclude predictable maintenance losses and may require extra coverage for risks such as overland flooding or sewer backup. Read the actual proposal and policy wording for your address.
Coordinate the effective date with the people closing the purchase
Ask your insurer, lender and lawyer what each needs and by when. Confirm the named insureds, property address, coverage start date and any mortgagee or loss-payee wording. FCAC notes that, subject to the policy, a mortgaged home policy will usually include a loss-payee clause naming the lender.
The start date should match the transaction instructions—not a guessed moving time. If the closing date changes, tell the insurer promptly and confirm the revised coverage in writing.
Greater Sudbury details worth raising early
Homes across Greater Sudbury range from urban properties near hydrants to rural or waterfront homes with private roads, wood heat, oil equipment, wells or seasonal access. Older houses may also have systems that have been repaired or replaced in stages. None of those facts automatically tells you whether a home is insurable. They are reasons to give the insurer accurate detail and allow time for follow-up.
The insurer cannot confirm coverage can begin by closing.
The quote depends on an inspection, repair, photograph or document that has not been completed.
The proposed policy excludes a risk that matters to the property or your intended use.
Your occupancy, rental or business plan is different from what was disclosed in the application.
The lender’s insurance requirement and the insurer’s documentation do not line up.
Do not solve an insurance concern by guessing at a fact or changing an answer to obtain a quote. Bring the issue to the insurer or broker and, where it affects a condition, financing or closing, to your real estate representative, lender and lawyer before the applicable deadline.
This is general real estate information, not insurance, legal or lending advice. Coverage, underwriting and transaction terms depend on the property, applicant, policy, lender instructions and signed agreement. Confirm your own requirements with the appropriate licensed professionals.
Your next step: Send the property details to your insurer or broker early, then put any unresolved requirement beside the condition and closing deadlines in your purchase plan. If you want help keeping those moving pieces organized, contact Chad Moore.
Expect Moore for Your Real Estate. — Chad Moore, REALTOR® — Lake City Realty Ltd., Brokerage
An MPAC property inspection is about the facts used in your assessment, not the condition check a buyer orders before purchasing. In this short video, MPAC explains why an inspector might visit and what they may verify: lot information, structures such as garages or pools, and sometimes details inside the home. MPAC says its inspectors identify themselves and explain the visit. If you're buying a property, my separate home-inspection guide covers the buyer's side of due diligence.
Quick answer: Ontario land transfer tax is part of the cash a buyer needs at closing. It is separate from the down payment and mortgage. The tax uses graduated rates, so only the portion of the purchase price inside each bracket is taxed at that bracket’s rate. Your real estate lawyer calculates and remits the final amount.
A buyer can have a comfortable monthly mortgage payment and still be short on closing day if the land transfer tax was left out of the plan. In Greater Sudbury, this is the provincial Ontario tax. Toronto’s separate municipal land transfer tax does not apply to a Greater Sudbury purchase.
How Ontario calculates land transfer tax
Ontario land transfer tax generally uses the value of the consideration. For a typical arm’s-length home purchase, that is often the purchase price, but purchase price is not a universal substitute for value of the consideration in every transfer. Ontario’s current general rates are:
0.5% on the portion up to and including $55,000;
1.0% on the portion above $55,000 up to and including $250,000;
1.5% on the portion above $250,000 up to and including $400,000;
2.0% on the portion above $400,000; and
2.5% on the portion above $2,000,000 when the land contains one or two single-family residences.
The examples below apply the provincial brackets only. They are planning figures, not a legal statement of adjustments.
Purchase price
Ontario land transfer tax before any refund
If the maximum $4,000 first-time buyer refund applies
$400,000
$4,475
$475
$500,000
$6,475
$2,475
$700,000
$10,475
$6,475
$1,000,000
$16,475
$12,475
Use the table to reserve cash, then ask your lawyer to confirm the actual figure for the property, ownership structure and transaction. Transfers involving assumed debt, a beneficial interest, family arrangements, new construction or other non-standard facts can require a different analysis.
What the Ontario first-time homebuyer refund changes
An eligible first-time homebuyer may receive a refund of all or part of the provincial land transfer tax, up to $4,000 for qualifying transfers on or after January 1, 2017. Ontario says a qualifying buyer must, among other requirements, be at least 18, occupy the home as a principal residence within nine months, never have owned an eligible home or interest in one anywhere in the world, and meet the citizenship or permanent-residence rules. A spouse’s ownership history and a non-qualifying co-purchaser’s interest can change the result.
At the current provincial rates, an eligible buyer can receive the full refund when the value of the consideration is $368,000 or less. Above that threshold, land transfer tax remains payable. When only some purchasers qualify, the refund is based on the qualifying purchaser’s proportionate interest, so have the lawyer confirm title shares and the claim.
The provincial rules do not necessarily use the same “first-time buyer” test as a federal savings program. Do not assume that FHSA or Home Buyers’ Plan eligibility proves eligibility for this refund. Review Ontario’s first-time homebuyer land transfer tax refund rules (opens in a new tab) and have your lawyer confirm the claim.
Build the number into the buying timeline
Before shopping: choose a realistic price range and calculate an initial provincial tax estimate at the top of that range.
Before writing an offer: keep the tax outside the down-payment total. Add legal fees, title insurance, inspections, appraisal or lender charges, moving costs and a reserve for adjustments.
After acceptance: tell your lawyer about every buyer who will take title and ask early about refund eligibility or non-resident issues.
Before waiving financing: confirm that the required cash is available and acceptable to the lender. A mortgage approval does not automatically cover closing costs.
Before closing: use the lawyer’s trust request and statement, not an online calculator, as the controlling amount.
What this article does—and does not—cover
This page goes deep on Ontario land transfer tax. It does not replace the broader Greater Sudbury buyer closing-cost guide, which covers legal fees, adjustments, insurance, inspections and moving expenses. For the final sequence from lawyer instructions to possession, continue to Closing & Moving Day. If a term on the lawyer’s estimate is unfamiliar, the Ontario buying glossary is the quickest reference.
Check the current rules: Tax brackets, refund conditions and non-resident rules can change. Recheck the linked Ontario pages and obtain transaction-specific legal advice before using any amount.
Turn the tax estimate into a complete buying budget
I can help you connect the price range, property type and Greater Sudbury search to the right due-diligence timeline. Your lender determines financing and your lawyer determines the tax and closing funds.
Buying or selling a home is a high-stakes decision. The right REALTOR® can reduce risk, bring structure, and help you make cleaner decisions. This is a proof-first checklist for Greater Sudbury — what to verify, what to ask, and what “good” looks like beyond personality, hype, or a polished social feed.
Client-first checklist · Proof over promises · Clarity over chaos
Start with the basics: make sure the person and brokerage are properly registered in Ontario and in good standing. This protects you from misrepresentation and gives you a clean place to start.
Use RECO’s public registrant search to confirm the agent/brokerage details: RECO Registrant Search
If someone gets defensive about being verified, that’s a signal. Professionals expect due diligence — they welcome it.
2️⃣ Start with proof — not promises
Every agent will tell you they care. Instead of promises, look for evidence: verifiable public reviews, real case studies, and specific feedback about communication and negotiation.
If an agent can’t show proof beyond a highlight reel, you’re being asked to bet your money on vibes.
For sellers, proof should connect directly to process. A strong result usually comes from the right Seller Consultation, clear pricing strategy, strong preparation, a structured launch, and calm offer review — not just luck.
3️⃣ Representation should be explained clearly (not rushed)
Before you sign anything, you should understand what it means to be a client versus a self-represented party, how representation agreements work, and how conflicts are handled.
What you should be able to explain back
Who represents who, and what services are included
How confidentiality works, and what must be disclosed
How remuneration is structured, and what you may owe (if anything)
What happens if the same brokerage represents both sides (and why that matters)
A simple test
If you can’t summarize your representation in two sentences, it hasn’t been explained well enough yet.
Good guidance is calm, clear, and documented. Pressure and vagueness are red flags.
For sellers, this matters because the paperwork is not separate from strategy. Listing agreements, seller directions, offer instructions, conditions, and closing details all need to be handled with clarity. If you want a plain-English overview of the documents buyers and sellers commonly see, review The Real Estate Forms Buyers and Sellers See in Greater Sudbury.
4️⃣ Look for a clear, written process
Structure removes chaos. A strong Realtor doesn’t just open doors — they help you think clearly at each decision point. Ask for the process in writing. If the answer is “don’t worry, I’ll handle it,” that’s not a process.
5️⃣ Local knowledge should be specific — not generic
“Sudbury market is strong” is not guidance. Real insight explains why two pockets can price differently, why one area moves faster, and how property types behave over time.
“Which comparable homes actually set today’s value — and why?”
“What would cause this home to sit longer than expected?”
“What do buyers typically miss in this area?”
“What are the common deal-breakers for this property type?”
For sellers, local knowledge should show up in practical advice: how to set the right price lane, whether the first week is likely to create urgency, which buyer pool the home appeals to, and what could create friction during showings or inspections. That is why pages like How Long Does It Take to Sell a Home in Sudbury? and Why the First Week on Market Is Critical in Sudbury are useful tests of whether strategy is grounded locally.
6️⃣ Tools should reduce noise — not create it
MLS® access is standard. What matters is how listings are filtered, tracked, and organized so you don’t miss opportunities or burn out from decision fatigue.
Clear pricing rationale (not “let’s test the market”)
A marketing plan you can actually read and measure
Offer strategy and protection plan (timelines, deposit, conditions)
For sellers, tools should support decision-making. That includes a realistic Home Valuation, a launch plan that can be measured, and market feedback that helps identify whether a listing has a traffic problem, an offer problem, or a value-perception problem. I explain that diagnosis further in Why Your Sudbury Home Isn’t Selling.
7️⃣ Negotiation is where a clear plan matters
Marketing can bring attention. Negotiation can help protect value. Ask how they handle competing offers, inspection issues, conditions, and timelines — and listen for calm structure, not bravado.
Clear risk management (what you gain vs. what you give up)
Clean paperwork and timelines (fewer surprises later)
Negotiation based on facts and leverage, not ego
Back-up planning (what happens if the deal wobbles)
A good negotiator should also know how to explain conditions, not just price. Sellers should understand the difference between the highest offer and the strongest offer, especially when financing, inspection, or sale-of-property conditions are involved. For more on that, review Conditional Offers in Sudbury and What Happens After Accepting an Offer in Sudbury.
Questions to ask any Realtor (copy/paste)
Can you show local case studies similar to my situation?
What is your exact step-by-step process — in writing?
How do you set and defend pricing (and what comps matter most)?
How do you handle competing offers and tight deadlines?
What tools keep me organized and competitive?
How do you reduce risk during conditions and due diligence?
How will communication work — and what response time should I expect?
What would you advise me not to do in this market (and why)?
️ Red flags worth taking seriously
Pressure to sign quickly without clear explanation
Vague pricing (“it’ll sell for what it’s worth”) with no data
No written plan, no documentation, no structure
Defensiveness when you ask for proof or verification
Over-promising outcomes (especially on timelines or sale price)
Ready for a real conversation?
If you want clarity about your next move — buy, sell, or both — start with a short, honest conversation.
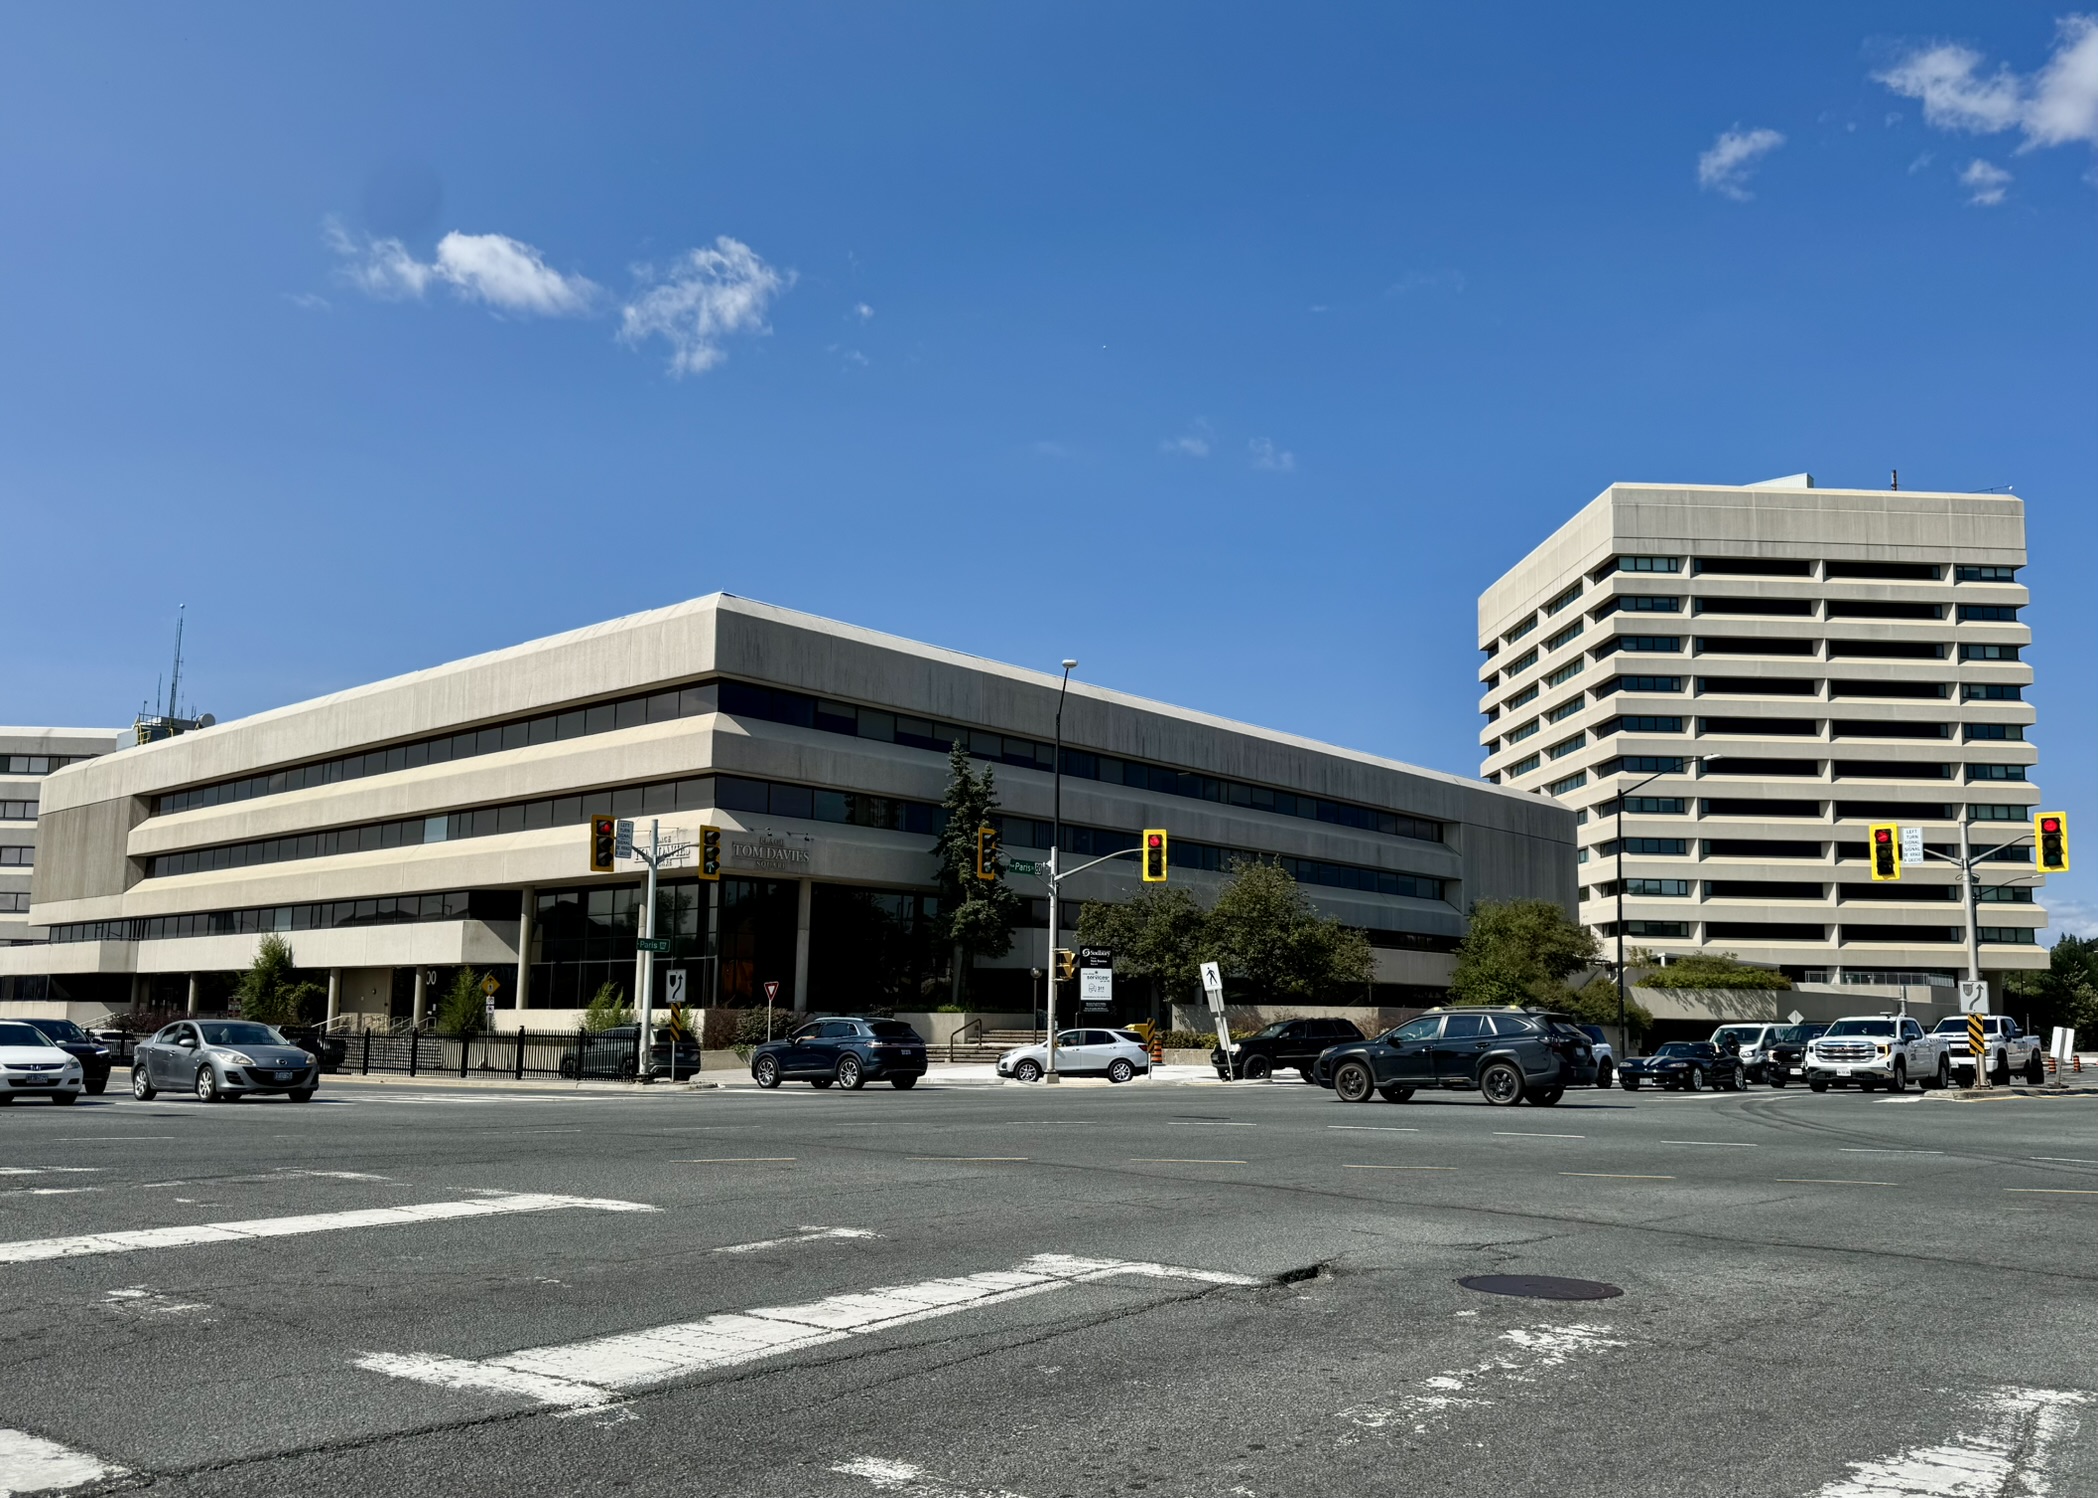
Tom Davies Square, August 2025. Photo: Platttenbau, CC0, via Wikimedia Commons. Display cropped to fit.
By Chad Moore · Updated October 14, 2026
In conversations with clients and neighbours, five subjects keep coming up ahead of Greater Sudbury’s election: roads, the event centre, the city’s response to this year’s winter storm and spring flooding, homelessness and addiction, and gaps in municipal services. In outlying communities, the lack of services and disparities between communities are particular concerns.
If accessibility matters in your home search, a listing's “accessible” label isn't enough to tell you whether the space will work. In this CREA conversation, REALTOR® Jeffrey Kerr starts with the person's specific needs, then looks at entrances, bathrooms and whether a home can be modified. The full episode runs 44 minutes; the practical entrance-and-bathroom discussion begins around 15 minutes. My guide to reading a Sudbury MLS® listing can help you sort out what to verify before a viewing.
When I sit down with a first-time buyer in Greater Sudbury, I put each rebate and savings tool on a separate line. They can help, but they are not interchangeable: each has its own first-time-buyer test, timing and paperwork. Before you count a possible refund toward your offer, let's confirm which programs may apply and when the money would actually be available.
Start with the purchase budget, not the rebate
Build the plan from income, debt, down payment, closing costs and an emergency reserve. A rebate can reduce a qualifying cost, but it should not make an otherwise uncomfortable payment affordable.
Ontario land transfer tax refund
Ontario says qualifying first-time purchasers may receive all or part of the provincial land transfer tax back. Prior ownership anywhere in the world, a spouse's ownership history, citizenship or permanent-resident status, occupancy timing and ownership shares can affect eligibility.
Questions for the lender and lawyer
Ask the lender which federal tools fit the mortgage, and ask the lawyer to confirm Ontario refund eligibility and how it will be claimed. Keep the eligibility decision with the professionals responsible for it.
A practical Greater Sudbury sequence
Get a written financing range, estimate closing costs without assuming a refund, confirm program eligibility, then choose a search budget that leaves room for repairs, utilities and winter maintenance.
This is general information, not a mortgage recommendation. Rates, qualification and product terms depend on the borrower, lender and application date.
Compare the major first-home tools
Programs a qualifying Ontario first-time buyer may investigate
Program
Potential benefit
Planning point
Ontario land transfer tax refund
Up to $4,000 for a qualifying first-time purchaser
Prior ownership, spouse history, ownership share, occupancy and status rules matter; apply within the required period.
First Home Savings Account
Deductible contributions and a tax-free qualifying withdrawal
Opening the account starts participation-room calculations; first-year room is $8,000.
Home Buyers' Plan
Up to $60,000 withdrawn from RRSPs by an eligible participant
Withdrawal and repayment rules apply; FHSA and HBP can be used for the same qualifying home.
Federal home buyers' amount
Non-refundable income-tax credit for a qualifying buyer
It may reduce tax owed for the purchase year; it is not cash available at closing.
New-home GST/HST rebates
Potential tax relief for an eligible new or substantially renovated home
Buyer, property and agreement dates matter; an ordinary resale home does not qualify for the first-time new-home rebate.
Ontario's refund changes the closing-cost calculation
A qualifying buyer may receive up to $4,000 of provincial land transfer tax relief. Ontario states that qualifying purchases above $368,000 still pay tax on the amount not covered by the maximum refund. When one buyer qualifies and another does not, the eligible share can limit the refund. Ask the lawyer to calculate the actual amount for the proposed ownership structure.
FHSA and HBP solve different savings problems
An FHSA combines a deduction for qualifying contributions with a tax-free qualifying withdrawal. The HBP uses eligible RRSP funds and creates a repayment obligation. Account room, holding periods, withdrawal forms and the buyer's tax situation can affect the result, so the plan should be built before an offer deadline.
Home buyers' amount: a tax credit, not closing cash
The federal home buyers' amount is a non-refundable income-tax credit for a qualifying purchase. It can reduce federal tax you owe; it is not a cheque to use for the deposit or legal bill. CRA lists a claim amount of up to $10,000 for the 2025 tax year. Ask your tax professional to check the rules and amount for the year you buy.
New-home GST/HST rebates need their own check
If you are buying a new or substantially renovated home, the federal first-time home buyers' GST/HST rebate may apply, depending on the buyer, home and agreement dates. It does not apply to an ordinary resale home. Ontario also has a temporary enhanced new-housing rebate for qualifying transactions. Ask the builder, lawyer and tax professional to put the eligibility and net-price calculation in writing; do not assume an advertised rebate is cash in hand.
Use the programs in the right order
Set an affordable purchase and monthly-payment range without rebates.
Ask a lender or mortgage professional which account withdrawals fit the financing plan.
Ask the lawyer to confirm Ontario refund eligibility for every proposed owner.
Keep cash for legal fees, adjustments, moving, repairs and an emergency reserve.
Complete required forms and retain account and closing records.
A program may reduce tax or allow access to savings, but the money cannot simultaneously fund the down payment, closing costs, renovations and an emergency reserve. Put each expected dollar in one line of the budget and confirm when it is actually available. A tax deduction may affect a future return; it is not the same as cash in the account on closing day.
Program rules can also interact with the purchase date, occupancy, a spouse's history and the ownership structure. Confirm eligibility before relying on the amount in an offer strategy. These are October 2026 program snapshots; check the official rules and your professional advice for the purchase you actually make.
A price ceiling is only one part of a useful home search. Bedrooms, bathroom layout, parking, condition and location decide whether a home actually works for you. The more requirements you combine, the more carefully you need to test your budget against homes currently available.
There is no reliable city-wide surcharge for a garage, another bedroom or waterfront. Each property's location, size, condition and competing listings affect its price. Start with the features you need, then compare actual homes and recent comparable sales with your lender-approved range.
Separate needs from preferences
Write down the features that cannot change: perhaps enough sleeping space, an accessible entrance, a practical bathroom arrangement or a commute you can manage. Put preferences such as a second garage bay, a finished basement or a larger lot on another list. This makes a thin search easier to adjust without losing what matters most.
Be specific about how you will use the space. A listed bedroom count does not show room dimensions or whether the layout works for your household. "Two bathrooms" may mean different combinations of full and partial baths. Photos cannot tell you whether parking, storage or a home office will work day to day. Confirm these details in the listing and at the property.
Test one feature combination at a time
Begin with your location, price ceiling and non-negotiable features. Then try a second search with one preference removed. Compare the number and condition of homes that remain. If adding a garage or another bedroom leaves very few options, you can widen the area, revise the timing, change a preference or discuss a different price range with your lender.
Do not use one asking price as proof of a market premium. Compare homes of similar type, size, location and condition, and distinguish asking prices from prices at which comparable homes actually sold. A small set of sales may be too mixed to support a precise feature premium.
What to check for popular features
Bedrooms and bathrooms: Check room dimensions, layout and the type of each bathroom, especially if the listing's shorthand makes the home look more functional than it is.
Garage and parking: Confirm usable dimensions, vehicle access, storage, winter clearance and whether the structure is part of the property being sold.
Larger lots or acreage: Look beyond the lot size. Ask about access, services, boundaries, zoning and the ongoing work of maintaining the land.
Waterfront: Verify the nature of access, shoreline conditions, seasonal use, insurance and any restrictions before treating a listing as equivalent to another waterfront home.
Move-in condition: Budget for inspections and foreseeable repairs. An apparently lower purchase price can leave less room for the work a home needs.
Keep the complete cost in view
Your purchase limit needs room for more than the sale price. Ask your lender to test the monthly payment for a home you would actually buy, and account for closing costs, taxes, insurance, utilities and likely maintenance. If a property needs repairs or uses a well, septic system or other private services, investigate those costs before making an offer. The right comparison is the total commitment, not simply the highest price your pre-approval displays.
Make a short list you can act on
Pick two or three Greater Sudbury areas and save examples that meet your needs. For each one, note its asking price, condition, layout, days on market and any feature that would change your ongoing costs. Then compare recent sales with similar homes. That exercise gives you a working budget for your own search without pretending that one city-wide price band fits every feature combination.
Source and timing: This is an evergreen planning guide. It makes no claim about a current MLS feature premium, sold-home share or guaranteed buying range. Confirm current listings, comparable sales, financing, property details and professional advice at the time of your decision.
Before a Greater Sudbury buyer gets the keys, I would start with the agreement. A pre-closing visit is a chance to compare the home, its inclusions and any agreed repairs with what you bought. It is not a replacement for the earlier home inspection or a time to make a side deal at the property.
Prepare before the visit
Bring the agreement of purchase and sale, amendments and a short list of inclusions, exclusions and repairs. If you want an inspector, contractor, family member or anyone else to attend, ask first: the seller still owns the property before closing, and additional visitors need permission. RECO explains the purpose and access limits of pre-closing visits.
Charge your phone, take a small flashlight and leave enough time to look at areas that were hidden by furniture or belongings on earlier visits. The written agreement is the checklist; a preference, such as wanting a room repainted, is different from an obligation the seller actually agreed to.
Work through the home and record what you see
Check the included appliances and fixtures, agreed repairs, visible condition and major systems where access and time allow. Photograph a concern and note when and where you found it. Do not move or alter the seller's property. This is a practical comparison, not a test that can reveal every concealed or intermittent defect.
Final walkthrough checklist
Area
Check
Record
Agreement items
Inclusions, exclusions and agreed repairs
Missing item, incomplete work or supporting receipt
Condition
Material new damage, water, debris and cleanliness terms
Location, photograph and time noticed
Systems
Lights, plumbing fixtures, heating or cooling and included appliances where practical
What was tested and what did not operate as expected
Access
Keys, remotes, codes, manuals and vacant areas
What the agreement requires and what remains outstanding
If something appears wrong, raise it before closing
Tell your real estate representative promptly and send the photographs and the relevant agreement term. I can communicate with the seller's side, but your lawyer must advise on contractual remedies and closing instructions. Do not negotiate directly at the property, withhold funds on your own or start repairs before you have legal advice.
If weather or access prevented a meaningful check, document that too. A pre-closing visit cannot replace conditions you needed earlier. For the wider sequence between acceptance and possession, see what happens after an offer is accepted and our guide to the forms buyers and sellers see.
Closing day is a separate step
Confirm identification, insurance, funds and any remaining documents with your lawyer in advance. Arrange utility transfers and movers with some flexibility; keys are released only after completion is confirmed, not at a guaranteed hour on the calendar. RECO's key-release guidance is clear on that point.
Once possession is confirmed, photograph meter readings, check smoke and carbon-monoxide alarms, find the shut-offs and make sure the doors lock. If you discover a problem, record it before cleaning or repairing it and seek advice promptly.
Plan the last steps before moving day
If you are buying in Greater Sudbury, I can help you keep the agreement, visit, lawyer and moving timeline connected. Start with the Buyer Experience or ask me about your own closing plan.